California Mortgage Broker
Licensed mortgage broker serving homebuyers across California. Get matched with the right loan program for your situation.
Honest pricing, clear guidance, and a local team that picks up the phone — from first question to final signature.
Loan Types We Specialize In
Explore the loan programs available to California home buyers and homeowners.
Cities We Serve in California
Explore local mortgage guidance for communities across California.
Serving Homebuyers Across California
We work with homebuyers and homeowners all over California, from Sacramento down to San Diego and everywhere in between. Whether you’re looking at a single-family house in the suburbs, a condo in the city, or a multi-unit investment property, we handle the full range of loan programs—conventional, FHA, VA, jumbo, and non-QM options. We also help clients with refinancing, second homes, and properties held in trusts or LLCs. Our focus is on structuring loans that actually fit your situation, not just closing the transaction.
What Buying a Home in California Is Really Like
California is a patchwork of different markets, and the way we approach financing here has to reflect that. In Sacramento, there’s a mix of newer subdivisions and older homes—most people don’t realize this, but older properties can trigger appraisal issues, especially if there are visible repairs or additions that weren’t permitted. We get out in front of those details so you’re not blindsided halfway through the process.
In the Bay Area, condos and townhomes are everywhere. A lot of buyers overlook this, but not every condo project is eligible for all types of financing. Project approval can hang up an otherwise solid loan, so we check the HOA’s documentation and approval status early. For buyers looking at two- to four-unit homes in places like Los Angeles or Long Beach, rental income can sometimes help with qualifying, but lenders want to see proper leases and realistic market rents. There’s usually a couple different ways to approach this, and we walk through those options so you can see what actually makes sense.
Down the coast and around Lake Tahoe, second homes and vacation properties come up often. These bring their own twists—lenders look at access, seasonality, and sometimes even the type of road leading to the property. In the Central Valley and some rural areas north of Sacramento, USDA loans are possible, but eligibility maps shift, and the property type has to fit. In parts of Orange County and San Diego, you might run into coastal insurance needs or flood zones, which can affect qualifying and upfront costs.
Competitive offer situations are the norm in many parts of California, especially for homes that are priced right. The right setup upfront can save you a lot long-term, and speed and execution matter in this market. We structure loans based on your goals, not just the transaction, so you’re positioned well no matter what part of the state you’re buying in.
How We Help California Buyers and Homeowners
First-time buyers in California come to us with a mix of excitement and uncertainty, especially in markets where homes move fast or where down payment assistance is critical. We spend time upfront explaining what actually matters—how different programs work, what’s realistic for your situation, and how to avoid common mistakes that catch new buyers off guard. The strategy behind the loan matters just as much as the rate.
Move-up buyers and those downsizing usually have a home to sell or equity to move around. Timing is everything—lining up the sale and new purchase, working around contingencies, and managing liquidity so you’re not caught in a bind. This is where having the right lender really helps. We look at bridge loan strategies, recasting options, and ways to keep your offers strong without overextending.
If you’re self-employed or rely on commissions, California lenders want to see a pattern in your income, not just what you made last year. We go deep into your documentation before you ever make an offer, so there are no surprises once you’re in contract. For investors or buyers of multi-unit properties, rental income and property type make a big difference in how we structure the loan—sometimes it’s worth looking at non-QM programs, sometimes conventional is more flexible, depending on your goals.
People looking to refinance come to us with all kinds of objectives—lowering their payment, pulling out equity, or just getting rid of mortgage insurance. We walk through the options so you can see what actually makes sense based on your plans, not just what sounds good on paper. And for buyers in multiple-offer situations, we know that in Sacramento, the well-priced homes don’t sit long. In this market, speed and execution matter. We’re not just looking at the loan—we’re looking at your overall plan.
Regions We Serve in California
California’s real estate landscape is as varied as it gets. In the Bay Area—places like San Francisco, Oakland, and San Jose—condos and older single-family homes are common, and buyers often have to navigate tight inventory and strict HOA requirements. In Los Angeles and Orange County, you’ll see everything from hillside homes with unique construction to multi-unit properties in denser neighborhoods. Financing here often means structuring around rental income or navigating high-balance loan limits.
The Central Valley, including cities like Sacramento, Fresno, and Bakersfield, has a wide range of property types—newer developments, rural properties, and older homes that sometimes raise appraisal issues. USDA eligibility comes up more here, as do manufactured homes and properties with acreage. Inland Empire buyers in Riverside and San Bernardino often deal with newer tract homes, but also need to be aware of Mello-Roos taxes and newer community infrastructure that can affect qualifying.
Down south, San Diego brings a mix of coastal condos, single-family homes, and vacation properties. Insurance requirements, flood zones, and second-home guidelines are part of the conversation. Up north, in areas like Lake Tahoe and the Sierra foothills, seasonal access and property condition can shape loan options. Each region has its own quirks—this is where working with the right lender makes a difference.
Programs Available to California Buyers
We work closely with the California Housing Finance Agency (CalHFA), which offers a range of options for buyers who need extra assistance. The CalHFA FHA and CalHFA Conventional programs are designed for first-time buyers, providing down payment and closing cost support when needed. MyHome Assistance Program helps with upfront costs, while the CalPLUS programs add a bit more support for those who qualify. The Forgivable Equity Builder Loan is aimed at helping buyers build equity faster, especially in higher-cost areas. For those with student loans, the School Teacher and Employee Assistance Program can be a fit if you work in education.
Terms and program features change over time, and not every option fits every property or buyer. We take the time to confirm what’s currently available and walk you through your real options based on where you’re buying and what you actually need.
Talk to Someone Who Knows California
We started Green Haven Capital to bring a more honest and strategic approach to lending—something that’s especially important in a place as complex as California. If you want to talk through your options with someone who knows the state and its markets firsthand, reach out. We’re here for real conversations about what’s possible and what actually makes sense for you.
About Green Haven Capital Inc. NMLS# 173062
With 22 years of mortgage experience, we specialize in helping homebuyers navigate the mortgage process with confidence. Licensed in CA, CO, MD, OR, TN, TX, UT. Whether you’re buying your first home or refinancing, we’re here to help you find the right loan for your situation.
📞 (916) 476-6507 ✉ koto@greenhavencap.com 🌐 https://www.greenhavencap.com/
Frequently Asked Questions
what are calhfa programs for first time buyers in california
CalHFA, the California Housing Finance Agency, offers loan programs and assistance specifically for first-time homebuyers in the state. These programs can help with down payments and may offer more flexible qualification requirements than some traditional loans.
can i use rental income from a duplex in los angeles to qualify for a mortgage
Yes, lenders in California often allow you to use projected rental income from a two-unit property like a duplex to help you qualify for a mortgage. They’ll typically require documentation, such as a lease or an appraiser’s rent estimate, to count that income.
what are the fha loan limits in san francisco county for condos
FHA loan limits in San Francisco County are higher than in many other areas due to local home prices, and they do apply to condominiums. You’ll need to check the current year’s limits for exact figures, and the condo project must also meet FHA approval requirements.
what should i know about buying an older home in california with a mortgage
When buying an older home in California, lenders may require repairs or updates before approving the loan, especially if there are health or safety concerns. Renovation loan options are available if the property needs significant work.
can i get a mortgage for a vacation home near lake tahoe in california
It’s possible to finance a second or vacation home in areas like Lake Tahoe, but lenders may have stricter requirements than for a primary residence. You’ll need to show you can afford payments on both your main home and the vacation property.
We pride ourselves on clear communication and easy access when you need us. Answer a few quick questions and an experienced, local professional will guide you from here.
We keep you informed and supported every step of the way.
A quick call with a local advisor is the easiest first step. No pressure, no credit check.
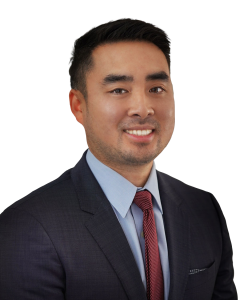
Kevin Oto
With over 20 years of experience, Kevin has established himself as one of Northern California’s most trusted mortgage advisors — helping homebuyers, homeowners, and real estate investors secure financing with clarity, confidence, and competitive pricing in any market.